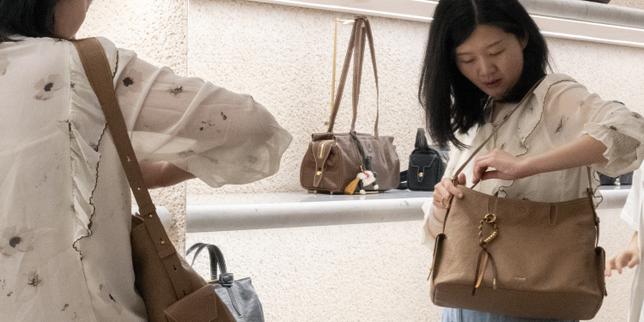
Every fashion journalist in Paris right now is high on their own supply.
They look at Songmont renting space in the French capital, staging pop-ups, and gathering crowds of digital-native shoppers, and they immediately reach for the lazy thriller script. They call it the Asian challenger brand. They call it the eastern insurgent coming for the crown of the reigning houses. They write breathless headlines about how legacy conglomerates like LVMH must be sweating in their marble executive suites over a direct-to-consumer leather goods label born on the internet. You might also find this similar coverage interesting: What Everyone Gets Wrong About the $200B South Korean Investment Deal.
It is a fairy tale. It is written by people who understand PR releases but do not understand balance sheets, pricing mechanics, or the brutal mathematics of global luxury.
Songmont is not going to dethrone Louis Vuitton. LVMH is not losing sleep over a brand shipping $300 minimalist bags to millennial professionals. Framing this as a pitched battle between a Chinese upstart and French heritage is sensationalist fiction. It masks the actual structural shift happening right now in retail. As reported in latest coverage by Bloomberg, the implications are widespread.
Let us strip away the hype and look at what is actually occurring.
The Lazy Narrative of the East-West War
The media loves a geopolitical narrative because it writes itself. David versus Goliath. East versus West. The old world order colliding with the nimble digital native.
When Songmont lands in Paris, the default cultural reflex is to treat it as an invasion. Commentators act as though Bernard Arnault is pacing his office floor worrying about a shortage of monogram canvas. This is fundamentally illiterate about how market tiers operate.
Luxury is not a single ladder where every brand occupies a rung and fights the brand immediately above or below them. Luxury is a archipelago of entirely separate economic islands. A consumer buying a Songmont bag is rarely choosing between that bag and a three-thousand-euro Dior saddle bag. They are choosing between Songmont and a mid-tier department store brand, or a local designer, or perhaps saving that money for a vacation.
To suggest that a functional, thoughtfully designed everyday bag brand is "aiguillonnant" (goading or spurring) LVMH is to misunderstand what LVMH actually sells. LVMH does not sell leather goods. It sells status, signaling power, historic rarity, and Veblen asset appreciation. Songmont sells smart utility, tactile quality at an accessible price point, and quiet aesthetics for people who have grown tired of screaming logos.
They are playing two entirely different sports under two entirely different sets of rules. One is selling entry tickets to an elite club. The other is selling high-functioning gear for the modern working day. Conflating them is lazy analysis.
Why Heritage Houses Are Not Sweating
Let us look at the numbers and the margins.
When a heritage house prices a bag at four thousand euros, they are not charging for leather and stitching. The raw materials and labor represent a tiny fraction of that sticker price. The rest is pure pricing power—the historic accumulation of cultural capital, celebrity endorsements, prime real estate rents on Avenue Montaigne, and decades of advertising dominance.
A brand like Songmont operates on entirely different unit economics. They rely on direct-to-consumer efficiency, digital acquisition funnels, lean inventory management, and high inventory turns. Their margin structure depends on volume and brand efficiency, not on artificial scarcity and astronomical price inflation.
I have watched companies burn millions trying to mimic the aura of heritage houses while trying to maintain mass-market accessibility. It is a financial dead end. You either commit to the absurd pricing power of true Veblen goods, or you compete on value, quality, and design intelligence. Songmont chose the latter. That is a smart strategy, but it poses zero existential threat to a multi-brand luxury conglomerate that derives its earnings power from high-margin leather goods and champagne portfolios.
Bernard Arnault does not check competitor spreadsheets for internet-born handbag labels. He watches macroeconomic shifts in China, currency fluctuations between the euro and the dollar, and global wealth concentration at the top one percent. A pop-up in Paris is good marketing, not a hostile takeover.
The Pricing Vacuum That Built Songmont
To understand why brands like Songmont are finding traction, we have to look at the massive vacuum left behind by traditional luxury houses over the past five years.
During and immediately after the pandemic, legacy luxury brands embarked on an aggressive, almost reckless pricing escalation. They raised prices year after year, sometimes twice a year, aiming to insulate themselves from inflation and artificially inflate their exclusivity quotient. A classic bag that cost two thousand euros suddenly cost four thousand.
In doing so, they abandoned a massive swath of consumers. They left behind the aspirational buyer—the young professional, the urban architect, the mid-level manager who used to save up for a seasonal luxury purchase as a career milestone. Those buyers were priced out. Not because they lost their taste, but because the math stopped making sense. Paying three thousand euros for a bag made of treated calfskin starts to feel less like an investment and more like a financial penalty for wanting nice things.
This is the vacuum that Songmont and similar clever mid-tier brands stepped into. They did not conquer the market through aggressive warfare; they simply walked through an open door that luxury houses left wide open when they abandoned the middle tier in pursuit of ultra-high-net-worth exclusivity.
When consumers realized they could get clean lines, modular designs, genuine leather, and thoughtful functionality for a fraction of the cost, they voted with their wallets. It was not a rebellion against France or heritage. It was a rational economic reaction to runaway luxury inflation.
The Architecture of Emotional Utility
Let us examine what Songmont actually does well, because dismissing them as a mere budget alternative would be a separate mistake. Their design philosophy is rooted in a specific kind of modern pragmatism.
Traditional luxury often demands that the user adapt to the object. The bag is stiff, delicate, heavy, or structurally rigid. It requires care, specific outfits, and careful handling. It is an ornament that happens to hold a phone.
Songmont built its reputation on modularity and functional transformation. Bags that can fold, reshape, or convert from a shoulder tote to a structured crossbody appeal directly to people whose lives do not fit inside a static box. The modern professional is moving between co-working spaces, airports, client meetings, and dinners. They need gear that bends to their reality.
This is what I call emotional utility. It is the quiet relief of owning an object that makes your daily friction disappear. There are no screaming monograms telling the subway car how much disposable income you possess. Instead, there is clever hardware, sensible compartmentalization, and soft leather that breaks in gracefully.
For years, fashion critics mocked practical design as boring. They argued that luxury required a degree of discomfort or impracticality to prove its worth. But consumer psychology has shifted. The people buying these bags are not looking to impress a boardroom full of snobs; they are looking to navigate a hectic Tuesday without carrying three different bags.
That is not a trend. That is an evolution in urban ergonomics.
Why Logomania Is Dying and What Replaces It
For decades, luxury sales were anchored by the logo. The bigger the monogram, the louder the signal. It was a straightforward way to communicate success in societies undergoing rapid urbanization and wealth creation.
That model is burning out. In mature urban centers across Asia, Europe, and North America, logo fatigue is real. When every secondary market platform is flooded with counterfeit or vintage monogram bags, the signal value of a loud logo plummets. It stops looking like wealth and starts looking like try-hard conformity.
Enter quiet design. But let us be precise—true quiet design is not just minimalism for the sake of looking minimalist. It is an appreciation for craftsmanship, silhouette, and tactile discretion.
When a brand succeeds by offering unbranded or subtly branded leather goods, it forces the consumer to evaluate the product on its own merits. Does the strap sit comfortably on the shoulder? Does the clasp operate with one hand? Does the leather smell right?
This shift terrifies mediocre legacy brands that relied entirely on a stamped canvas pattern to sell a product at a ten-thousand-percent markup. When the logo loses its hypnotic power, those brands have to compete on actual product excellence. Many of them have forgotten how to do that because they spent the last twenty years outsourcing product innovation to marketing departments.
Songmont capitalized on this transition early. They understood that the next generation of consumers values discretion over ostentation. They built a visual language around calm shapes and earthy tones. That is why their Paris pop-up drew crowds—not because they are destroying LVMH, but because they are filling a massive cultural appetite for understated competence.
The Brutal Economics of Modern Retail
Let us look at what happens next, without resorting to lazy predictions about who will win or lose.
Direct-to-consumer handbag brands face their own brutal ceilings. Scaling a brand internationally requires enormous capital expenditure on logistics, physical retail presence, localized marketing, and supply chain resilience. Running a few successful pop-ups in Paris is a brilliant marketing stunt, but maintaining permanent retail footprints in high-rent European capitals is a bloodbath for margins.
Rent on Rue Saint-Honoré or Avenue Montaigne does not care about your digital-native efficiency. Property owners demand top dollar, and European retail unions enforce strict labor laws. Many foreign brands discover too late that the romance of a Parisian flagship store comes with overhead costs that can crush a lean operating model.
Furthermore, as Songmont scales, they will face the exact trap that snared their predecessors: margin compression. To grow, they will need wholesale partners, department store shelf space, and heavier advertising budgets. Every single one of those steps dilutes the pure DTC margin advantage and forces them to raise prices.
Once you start raising prices to fund global expansion, you drift closer to the very territory occupied by entry-level legacy diffusion lines. And once you enter that arena, you are no longer the cool, smart secret discovered on the internet. You become just another brand competing for shelf space in a crowded, unforgiving marketplace.
This is the paradox of modern retail growth. To become big, you must adopt the machinery that makes big brands slow, expensive, and vulnerable.
The Real Lesson of the Paris Pop-Up
So let us stop pretending this is a war between David and Goliath.
Songmont coming to Paris is not an act of aggression against French luxury. It is a symptom of a much larger, healthier recalibration of the global accessories market.
The consumer is no longer a passive recipient of whatever price point a heritage conglomerate decides to drop from the sky. They are discerning, mobile, digitally literate, and deeply allergic to being overcharged for mediocrity wrapped in heritage marketing.
LVMH will continue to print billions selling ultra-luxury status symbols to the global elite. Songmont will continue to build a loyal following among pragmatic professionals who want beautiful, functional leather goods without remortgaging their apartments. Both can exist simultaneously because they serve entirely different human impulses.
The only people confused by this are the commentators who need a dramatic storyline to fill column inches. Ignore the hype. Look at the balance sheets, examine the utility, and stop looking for a war where there is simply a very efficient, well-executed market adjustment.
The future of accessories does not belong to the loudest logo or the most aggressive press release. It belongs to whoever respects the customer's intelligence and solves their daily friction with style. Everything else is just noise.


